Chapter 18 built the theory of convex sets and proved
its main theorems: that a compact convex set is the hull
of its extreme points, that a bounded polyhedron and a
polytope are the same thing, and that a feasible,
bounded linear program and its dual have the same
optimal value. This section proves none of that
again. It reads those theorems as statements
about the geometry of a solid with flat sides: what its
faces are, how they fit together, and what a linear
program looks like when the objective is a family of
parallel hyperplanes sliding across it. Everything here
is a corollary of Chapter 18 or a short argument on top
of it, and every citation points back there.
Throughout, the field is and the space is
with the dot
product, as in Chapter 18. A polyhedron is a set (Definition 18.9.2), with
whose rows we write ,
so that
is the list of inequalities . A
vertex of is an extreme point of
it (Definition 18.8.1), and
is the set of them. We use Chapters 16 and
18’s topological words — closed, bounded, compact — only
inside the results we cite; nothing here develops them
further.
Faces, cut
by a supporting hyperplane
A cube has six square sides, twelve edges and eight
corners, and each of them is the part of the cube
touched by a plane that has the whole cube on one side.
That is the picture to formalize. The tool is Chapter
18’s supporting hyperplane (Theorem 18.3.6): a
hyperplane through a point of a convex set with the set
in one of its closed half-spaces.
A face of a polyhedron is the part of it touched
by a hyperplane that does not cut into it.
Definition
22.3.1 (Face of a Polyhedron)
Let be a polyhedron. A face
of is a set of
the form for some and such that
for every . A face other
than itself is
called proper.
Clause by clause. The pair must be a
valid inequality for : the whole polyhedron
lies in the closed half-space .
The face is then what the boundary hyperplane
actually touches. Note that is allowed to be .
Two faces come free. Taking and makes the
inequality ,
valid everywhere, and : the whole polyhedron is a face of
itself. Taking and makes the inequality , again valid, and
:
the empty set is a face. These two are
the degenerate cases, and they are kept because the
theorems below are cleaner with them than without.
Chapter 18 §08 already has a notion of face for an
arbitrary convex set, Definition 18.8.2: a
convex subset that swallows every segment of passing through it at
an inner point. The two agree here in one direction at
once.
Examples, in , with the triangle of Chapter 18 §09.
- ,
. The
inequality is valid by the third row, and the face is
the slanted edge from to .
- ,
. Valid,
since on .
The face is the single point : the hyperplane
touches the
triangle at one corner.
- ,
. Valid by
the first row, and the face is the vertical edge .
- ,
. Valid,
but never attained: the face is .
A non-example by minimal change. In
example 1 replace by . The set is still a segment inside
, still convex,
and still a slice by a hyperplane. What fails is the one
clause the definition insists on: is
not valid for , since violates it.
The hyperplane cuts through the triangle instead of
resting against it, and the slice is not a face. It also
fails Definition 18.8.2: the
segment from
to passes
through at an
inner point but is not contained in the slice.
The reason faces are useful is that there are only
finitely many of them, and each is again a polyhedron
described by the same rows, some of
them turned into equations.
Proposition
22.3.1 (Faces Are Polyhedra, and There Are
Finitely Many)
Let with rows. For put Then:
- (a) every is a face of , and it is a
polyhedron;
- (b) every
non-empty face of equals for some ;
- (c) consequently
has at most non-empty faces, and
every face of is
a polyhedron.
Idea. For (a), add up the rows
indexed by : the
sum is at most on
, and a sum of
numbers each at most its bound hits the total bound only
if every one of them does. So one valid inequality
encodes all of at
once.
For (b), let
be a non-empty face and let collect the rows that
are tight at every point of . Certainly . For the
other inclusion we need a point of at which every row
outside is
slack; averaging finitely many points
of , one per slack
row, produces it. Then, given with , step
from
away from . The rows in are equations satisfied
by both points, so they survive the step exactly; the
rows outside have
room at , so
they survive a short step. But the step raises above , which no point of
may do.
Proof.
(a) Put
and , with the empty sums and . For , so the inequality is valid. If and , then
is a sum of non-negative
numbers, so each is zero and ; conversely
every
has . Hence is a face. It is
a polyhedron because each equation is the
pair of inequalities and
, so is cut out by
inequalities.
(b) Let be non-empty, with on
. Put Then by the definition of , and it remains to
prove .
First note that is convex: it is the
intersection of the convex set (Proposition 18.9.1) with
the solution set of a linear equation, which is convex
as the preimage of a point under (Proposition 18.1.1 (b));
an intersection of convex sets is convex by Proposition 18.1.1
(a).
Step 1: a point of with every row outside
slack.
For each
choose, by the definition of , a point with . If
let be any
point of .
Otherwise let be the number of indices outside and let , which lies in by convexity. For each
, every
term of is at most
and the term
is strictly
less, so .
Step 2: the step away from . Let and suppose,
for a contradiction, that . For
put . For we have ,
because , and , because
; hence
For put
and ; both
are minima and maxima of finitely many numbers. Choose
with , which is
possible (any
will do if ).
Then for , So . But since and . This contradicts the validity
of on . Hence and , so and .
- (c) There are subsets , so by (b) at most that
many non-empty faces. Each of them is a polyhedron by
(a), and the empty face is the polyhedron . This
proves the proposition.
The map is onto the non-empty faces but is very far
from injective: adding to a row that is already
tight everywhere on changes nothing, and
adding two incompatible rows gives .
Warning. A row of the
system need not be a side of the solid. In
the third row
is implied by the first two, since on . It defines no face
except the empty one: . So a polyhedron with rows can have far fewer
than sides, and
counting rows is not counting geometry. Conversely, Definition 22.3.1 never
mentions the rows at all, which is why Proposition 22.3.1 has to
prove that the faces can be read off them.
Vertices,
edges, facets
A non-empty face is a non-empty convex
set, so it has a dimension: , as in Chapter 18 §01, and is
the flat of
Proposition 18.1.4 — a
flat in the sense of Definition 22.2.1. The
graded vocabulary follows.
Definition
22.3.2 (Edge, Facet)
Let be a non-empty polyhedron. A face of
of dimension
is an
edge; a face of dimension is a
facet. A face of dimension is a single point, and
the next proposition shows that these are exactly the
vertices.
Proposition
22.3.2 (Three Descriptions of a Corner)
Let and . The following
are equivalent.
- (a) is a vertex of , that is, an extreme
point.
- (b) is a face of .
- (c) Among the rows
active at there
are linearly
independent ones, that is, is a basic feasible
point.
Idea.
- (a) and (c) are Theorem 18.9.2, already
proved. A one-point face is an extreme point by Proposition 18.8.4 (b).
For the remaining implication, take to be the active set:
if the active rows have rank , the system has as its only solution,
so ,
and Proposition 22.3.1 makes
that a face.
Proof.
(a) (c) is Theorem 18.9.2.
(b) (a). Write
with on
. By Proposition 18.8.4 (b),
applied with and , .
(c) (b). Let
be the
active set and
the matrix of active rows, of rank by hypothesis. Its null
space is by
Theorem 3.5.7, so
has
at most one solution; since is one, it is the only
one. Hence and
is a face by Proposition 22.3.1 (a).
This proves the equivalence.
So a corner of a polyhedron can be recognized three
ways: by convexity (it is not an average), by geometry
(a hyperplane touches there and nowhere
else), or by algebra (enough constraints are tight). The
three are used interchangeably from here on.
Bounded polyhedra are the ones with enough corners to
rebuild them. This is the bounded half of the
Minkowski–Weyl theorem, and it is the sentence this
whole section is arranged around.
Theorem
22.3.3 (A Bounded Polyhedron Is the Hull of Its
Vertices)
Let be a bounded polyhedron. Then is
finite and Conversely, every polytope is a bounded
polyhedron.
The same theorem applied to a face is what makes an
edge a segment between two corners — the statement that
lets one speak of walking along the edges of a
solid.
Proposition
22.3.4 (An Edge Joins Two Vertices)
Let be a bounded polyhedron and an edge of . Then for two
distinct vertices of .
Idea. An edge is itself a bounded
polyhedron, so it is the hull of its own vertices; those
are vertices of
because a face passes extremeness upwards. Being -dimensional, it sits on
a line, and the hull of finitely many points of a line
is the segment between the outermost two.
Proof. By Proposition 22.3.1, is a polyhedron, and it
is bounded because . By Theorem 22.3.3, with
finite, and since it has a dimension. By the
remark after Definition 22.3.1, is a face of in the sense of Definition 18.8.2, so Lemma 18.8.3 gives : every vertex of is a vertex of .
Fix . By
Proposition 18.1.4,
with , and , so
for
some .
Every point of
lies in ,
hence is
for exactly one , the map being injective because . Let be
the parameters of the points of , a
non-empty finite list. A convex combination
equals , and lies in
;
conversely each is for some . Hence,
writing
for the segment of Chapter 18 §01, If then
is a single point and , contrary to hypothesis; so , and both are
vertices of . This
proves the proposition.
Two face
lattices, computed
Faces are ordered by inclusion, and the resulting
picture — which face lies in which — is the face
lattice of the polyhedron. It is the
combinatorial skeleton of the solid. Here it is in full
for the two standard examples.
Example
(The faces of a cube)
Let , described by the rows and . Find
all faces of and their
dimensions.
Solution. By Proposition 22.3.1 (b)
every non-empty face is some . A set of rows says, for each
coordinate ,
either nothing, or , or , or both; the last makes . So the
non-empty faces are indexed by sign
vectors : Each is non-empty: the
point with where and elsewhere lies in it. Distinct sign vectors
give distinct faces, because exactly when
the coordinate
is constantly
on . So has exactly
non-empty
faces, one for each sign vector, together with .
Let and . Then
is the flat , a coset of :
it contains ,
and conversely contains the point
with for and for , together with
for every
, whose
differences from
span . By Proposition 18.1.4,
.
So the faces of dimension are the sign vectors
with exactly
zeros, and there are of
them. For :
vertices (), edges (), facets () and the cube
itself, and . Every vertex is a sign vector in each coordinate,
matching what Example (The cube and the cross-polytope)
found by the rank test.
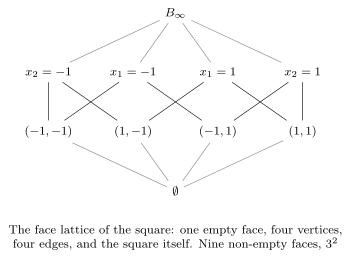
Here is the resulting lattice for the square ,
with at
the bottom and the square at the top, and a line drawn
when the lower face is contained in the upper one.
Example
(The faces of a simplex)
Let be the
standard simplex (Definition 18.1.2),
described by the
rows
together with and . Find all faces of .
Solution. The last two rows are
tight at every point of , so including
them in changes
nothing. A face is therefore for determined by a set
of coordinates forced to zero: Write . If the
conditions
and
clash, so . If , then consists of the
vectors
supported in with
, which by Theorem 18.1.3 is
exactly , a copy of .
Its dimension is , by the computation of after Proposition 18.1.4.
Distinct non-empty give distinct faces,
since
exactly for .
So the non-empty faces of are indexed by
the non-empty subsets , and there are of them: vertices, edges, and so
on up to
itself. For ,
the tetrahedron of dimension has non-empty faces.
The contrast is the point. The cube’s lattice is the
set of sign vectors; that of the simplex is the set of
non-empty subsets. A cube in dimension has vertices and facets; a simplex has
vertices and
facets. The
cube’s corners grow exponentially with , those of the simplex
only linearly.
Quick check. How many faces does a
triangle in
have, counting the empty face and the triangle
itself?
Solution. Eight: , three
vertices, three edges, and the triangle. Count directly
from Proposition 22.3.1 (b),
writing the triangle as the polyhedron cut out by its
three sides: is the
triangle, each single row gives one side, each pair of
rows gives the corner where those two sides meet, and
all three rows together give . That is non-empty
faces, plus . The count
matches Example (The faces of a simplex)
with , whose
non-empty faces are indexed by the non-empty subsets of
the three corners.
A linear
program, seen
Fix
with . The
level sets of the objective are parallel affine
hyperplanes, one for each , and they sweep
across as
grows,
moving in the direction . Maximizing over a polyhedron
means pushing the
sweeping hyperplane as far as it will go while still
touching . Two
things can happen: it escapes to infinity, and the
program is unbounded; or there is a last hyperplane that
touches, and what it touches is a face.
Proposition
22.3.5 (The Optimal Set Is a Face)
Let be a polyhedron, , and suppose
attains a
maximum on . Then the set of maximizers
is a non-empty face of . If is bounded, contains a
vertex of .
Proof. By the definition of a
maximum, for every , and is non-empty. That is Definition 22.3.1
verbatim, so is a face.
Suppose is
bounded. Then is a bounded polyhedron by Proposition 22.3.1, and
non-empty, so by Theorem 22.3.3 (a
non-empty set is not the hull of the empty set). By the
remark after Definition 22.3.1 and Lemma 18.8.3, , so any
point of is a vertex of lying in .
The last sentence is Corollary 18.8.6 read
geometrically, and it says a little more than that
corollary: not only is some maximizer a vertex,
but the whole set of maximizers is a face — a
single vertex when the optimum is unique, and otherwise
an edge or a larger face, up to all of when . A linear program
with a non-unique optimum has a positive-dimensional
optimal face, and every point of it is optimal.
An algorithm now suggests itself: start at a vertex,
and as long as some edge leaving it increases the
objective, walk along that edge to the vertex at its
other end (Proposition 22.3.4
guarantees there is one, when is bounded). That is
the idea of the simplex method,
sketched in Chapter 18 §09 after Corollary 18.9.3.
No algorithm is developed here or anywhere in
this book: Chapter 24 is where this book’s
algorithms live, and it treats the numerical linear
algebra of elimination, least squares and eigenvalues,
not linear programming. What this section supplies is
the geometry an algorithm would exploit.
Example
(A linear program and its picture)
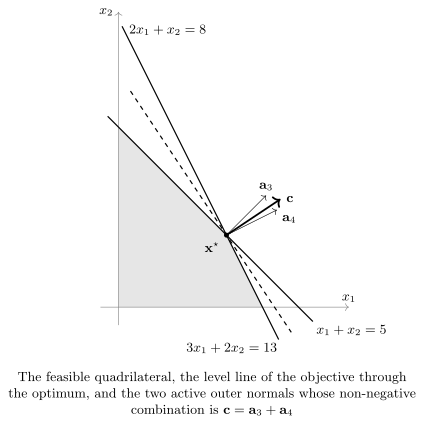
Maximize over Find the vertices, the optimum, the optimal
face, and the dual optimal solution.
Solution. Number the rows (1) , (2) , (3) , (4)
.
No two rows are multiples of each other, so each of the
pairs
gives one basic point, which we test against the other
two rows: For the last pair, subtracting (3) from (4)
gives ,
hence . By
Proposition 22.3.2 the
vertices are ,
, and . is bounded, since on
it, so by Theorem 22.3.3 it is the
quadrilateral .
The objective takes the value at , at , at and at , so by Proposition 22.3.5 the
maximum is , at
,
and the optimal face is . Since only one
vertex achieves
and the face is the hull of its vertices, the optimal
face is the single point : the optimum is
unique.
The rows active at are (3) and
(4), with outer normals and . And so is a candidate for the dual. In the notation
of Definition 18.6.2, with
the rows and and , the dual
asks to minimize subject to , , . At both constraints are equalities and the
value is , which matches. By Corollary 18.6.2 (a),
and
are both
optimal, and no further checking is needed.
What the
dual variables are, geometrically
The example ended with an identity worth isolating:
the objective vector was a non-negative
combination of the outer normals of the constraints
active at the optimum, and the coefficients were the
dual optimal solution. That is the geometric content of
duality, and Chapter 18 has already done all the
work.
Recall Chapter 18 §06’s pair of programs, with , , : The feasible region of (P) is the polyhedron
with the rows
and the rows
.
The outer normal of a row is the vector
on its left-hand side: for the -th constraint and for the sign
constraint on .
Proposition
22.3.6 (Dual Variables Are the Weights of the
Active Normals)
Let
be an optimal solution of (P). Then there are and with and such that where whenever , and whenever . That
is, is a
non-negative combination of the outer normals of the
constraints active at , and
the weights are an optimal solution of (D).
Idea. Strong duality hands over an
optimal for (D);
the slack is non-negative because is dual feasible, and
rearranging is the displayed identity. Complementary
slackness is exactly the statement that the weights
vanish on the inactive constraints.
Proof. Since is feasible,
(P) is feasible, and for every feasible , so (P) is not
unbounded. By Theorem 18.6.3 (b), (D)
is therefore feasible, and by Theorem 18.6.3 (a) both
programs have optimal solutions with equal optimal
values; let be
an optimal solution of (D). Then and , so . Reading the -th coordinate of as , we get
, and hence Both and are optimal, so Theorem 18.6.5 applies:
its condition (i) says forces ,
which is the contrapositive of “ forces ”; its condition (ii) says forces
,
that is .
This proves the proposition.
So a dual optimal solution is a certificate
written in normals. The hyperplane supports the feasible region at , by Theorem 18.6.1 and
equality of the optimal values, and Proposition 22.3.6 says
how its normal
is assembled from the normals of the facets meeting at
.
Increasing
loosens the -th
constraint, and
bounds the gain: the dual feasible
region does not mention at all, so stays dual feasible
when is raised
to , and Theorem 18.6.1 then caps
the objective of every point feasible for the loosened
program at , the old optimal value plus
.
That is also
the exact rate of gain, its shadow
price in the economists’ phrase, says more, and
this book does not prove it; nothing here uses it, and
it can fail. Take , ,
, and , so that (P)
maximizes subject
to written
twice and .
Its optimum is ,
and is
dual feasible with , hence dual optimal by Corollary 18.6.2 (a);
but raising
leaves the second copy binding and the optimum at , a gain of against . The same pair
shows which half of complementary slackness is
available: Theorem 18.6.5 (i) says
forces
row tight, so a
constraint slack at the optimum has
, and that
is what Proposition 22.3.6
records. The converse is the trap — here while row is tight.
Polyhedra
without corners
Boundedness is doing real work in Theorem 22.3.3, and the
failures are worth seeing.
Example
(A slab, and a quadrant)
- (a) Find the faces
of the slab , and its
vertices.
- (b) Show that does not exist for the quadrant , although has a vertex.
Solution.
(a) has the two rows and . By Proposition 22.3.1 the
non-empty faces are among , ,
and . So there are three non-empty
faces: and two
parallel planes, of dimensions , , . There is no face of
dimension or
. In particular
has no
vertices: at any the active rows are among , of rank at most
, so Theorem 18.9.2 denies a
vertex. Hence , and Theorem 18.8.5 indeed
needs compactness. Note also that is attained, on the whole
face ,
which contains no vertex: the last sentence of Proposition 22.3.5 needs
boundedness too.
(b) The point
is a vertex
of : the two
active rows are independent, so Theorem 18.9.2 applies.
It is the only one, since at any other point of at most one row is
active. But for every and there, so the objective is unbounded above
and no maximum exists. A polyhedron can have corners and
still have no optimum.
Warning. “Vertex” and
“corner of the picture” can both be empty words for an
unbounded polyhedron. The slab above is a
perfectly ordinary convex solid, closed, with a genuine
boundary, and it has no vertices, no edges, and no
bounded face. Nothing in this section rebuilds it from
finitely many points, and nothing should: by Theorem 18.9.5 (a) a
polyhedron is a polytope exactly when it is bounded. The
general finite description of an unbounded polyhedron
needs directions as well as points — every non-empty
polyhedron is a polytope plus a finitely generated cone
— which Chapter 18 derives from Theorem 18.9.5 (b) in Exercise (C1: Unbounded polyhedra),
and which is not pursued here.
Exercises
A. Check your
understanding
Exercise
(A1)
- (a) State Definition 22.3.1, and
say which pair exhibits itself as a face and
which exhibits .
- (b) True or false: a
polyhedron given by inequalities in has exactly non-empty faces.
Justify your answer.
- (c) Give the three
equivalent descriptions of a vertex from Proposition 22.3.2.
- (d) True or false:
if a linear program over a bounded non-empty polyhedron
has two distinct optimal solutions, it has infinitely
many. Justify your answer.
- (e) How many faces
of dimension does
the cube
have?
Solution.
(a) A face of a
polyhedron is a
set for some with valid
on all of . The
pair gives
; the pair
gives .
(b) False; is only an upper
bound (Proposition 22.3.1 (c)).
The map need not be injective, and some may be empty. The
warning after that proposition has rows in and only four
non-empty faces: the polyhedron, two edges and one
vertex.
(c) is a vertex
when: it is an extreme point of ; or is a face of ; or among the rows
active at there
are linearly
independent ones.
(d) True. The
optimal set is a face (Proposition 22.3.5),
hence convex, so it contains the whole segment joining
the two optimal points, and a segment with distinct ends
has infinitely many points.
(e) By Example (The faces of a cube)
with , : .
B. Practice
Exercise
(B1: Vertices and faces of a region)
Let Find all vertices of , list all of its faces,
and maximize over .
Solution. Number the rows (1) , (2) , (3) , (4)
.
No two are multiples, so each of the six pairs gives a
basic point: For the last pair, twice (3) minus (4) gives
, so and . By Proposition 22.3.2 the
vertices are ,
, and , so is a quadrilateral, not
a pentagon; two of the six basic points are infeasible.
is bounded (, on it),
so by Theorem 22.3.3.
By Proposition 22.3.1 (b)
every non-empty face is some . The four singletons
give the four edges, computed directly: ; ; , where gives and gives , a segment from to ; and , which in the same way is the segment
from to . The six pairs give
, ,
, ,
and , the two infeasible
basic points; every with three or more rows
gives ,
since no point of
has three rows active. So has ten faces in all:
, four
vertices, four edges and itself.
The objective takes the values , , , at , , , . By Proposition 22.3.5 the
maximum is ,
attained at
alone.
Solution. The optimum is . The
active rows there are (1), with outer normal , and (3),
with outer normal . In the notation of Definition 18.6.2 the
rows of are (3)
and (4) in that order, so the weight on is . Writing
with :
gives , so , and , so . Both are
non-negative, as Proposition 22.3.6
requires. Row (4) is inactive at , so its weight
is ; and
, so the slack on the second sign constraint
is .
So has rows
and , with and . The dual
solution read off is , which satisfies and so it is dual feasible, with value . Since the primal value at is also , Corollary 18.6.2 (a)
confirms that both are optimal.
Exercise
(B3: Faces of the cross-polytope)
Let , the cross-polytope of Example (The cube and the cross-polytope).
Determine the face for a single sign vector
, and its
dimension. How many facets does have?
Solution. For a single sign vector
, . Now , term by
term, so equality holds exactly when
for every ; and
on , as Example (The cube and the cross-polytope)
records. So forces and for every ; conversely those
conditions give . Writing with
, we get using Theorem 18.1.3. This is
a copy of ,
of dimension
by the computation after Proposition 18.1.4.
Since
— it contains
and every ,
and the differences span , so Proposition 18.1.4 gives
— each is a facet.
Distinct give
distinct facets, since is recovered from
by the
signs of the vertices .
There are no others. Every non-empty face is for a set of sign vectors, by Proposition 22.3.1 (b),
and if both lie in then . A point of that intersection
has , so whenever ; hence
the intersection is , of dimension at most , since at least one
index is missing. So has exactly facets: in it has vertices and facets, exactly the
reverse of the cube.
C. Going deeper
Exercise
(C1: A face of a face)
Let be a
polyhedron and a
face of .
- (a) Prove that every
face of is a face
of .
- (b) Deduce that the
faces of
contained in a fixed face are exactly the faces
of .
Hint: for (a), use Proposition 22.3.1 to
write both and
the face of in
the form .
Solution.
(a) We may assume
the face of is non-empty, since
is a face
of . Fix a system
with
and rows , . By Proposition 22.3.1 (b),
for some
. By part (a) of
the same proposition, is cut out by the original rows together
with the rows for . By (b) applied to with
this system, for some set
of those rows;
since the rows with are tight everywhere on , including them in
changes nothing,
so we may take . Then which is a face of by Proposition 22.3.1
(a).
(b) By (a), every
face of is a face
of , and it is
contained in .
Conversely let be
a face of with
, say
with on
. Then holds
in particular on , and so is a
face of .
Exercise
(C2: The two notions of face agree for a
polyhedron)
Let and let be a
non-empty face in the sense of Definition 18.8.2: is convex, and whenever
with
and , both
and lie in .
- (a) Let . Prove that .
- (b) Deduce that
is a face in the
sense of Definition 22.3.1, so the
two notions agree for polyhedra.
Hint: for (a), Step 1 of the proof of Proposition 22.3.1
produces a point of at which every row
outside is slack;
use it as the midpoint of a short segment.
Solution.
- (a) by the
definition of .
For the reverse inclusion, note first that is convex, so Step 1 of
the proof of Proposition 22.3.1
applies verbatim and yields with
for every .
Let .
If we
are done, so assume and put for . Exactly as in
Step 2 of that proof, for
and, for
small enough , for ; so . Fix such a . Then a combination with positive coefficients
adding to : indeed
the right side is . Both
and lie in and , so the face
property of Definition 18.8.2 forces
. Hence
and
.
- (b) By Proposition 22.3.1 (a),
is a face in
the sense of Definition 22.3.1.
Together with the remark after Definition 22.3.1, which
gives the other direction for every face, the two
notions coincide on polyhedra.
They do not coincide for general convex sets, and one
round set shows it. Let , let , let ,
and put , so that and . Since
is convex, Theorem 18.1.3 writes
every point of as
with
and , whence the first inequality by Theorem 11.1.5.
Equality with forces , hence dependent and ; so . Now
is a face of in the sense of Definition 18.8.2: if
with
and , then , and both
inner products are at most , so both equal and ,
with ; then forces . But no supporting hyperplane isolates
. If
on with ,
then ,
since gives
the face or ; testing the
inequality at the point of gives , so equality holds
in Theorem 11.1.5 and
,
.
Then , so lies in the face too,
and the face is not .
Exercise
(C3: The optimal face has no better vertex outside
it)
Let be a non-empty bounded polyhedron, , and let
be the
optimal face of Proposition 22.3.5.
- (a) Prove that .
- (b) Deduce that the
optimal value of the program equals , a maximum over a finite
set, and that this finite maximum is attained exactly at
the vertices lying in .
Solution.
(a) is a non-empty
bounded polyhedron by Proposition 22.3.1, so Theorem 22.3.3 gives
. By the
remark after Definition 22.3.1, is a face of
in the sense of
Definition 18.8.2, so Lemma 18.8.3 gives .
Substituting proves (a).
(b) By Corollary 18.9.3, is
finite, and it is non-empty by Theorem 22.3.3 since
.
Write for the
optimal value. Every vertex lies in , so for ; and by (a) contains a
vertex, at which . So the finite maximum equals
. A
vertex attains
it exactly when , which is exactly the condition
defining the optimal face.