Chapter 3 answered one question about a linear system
completely: has a solution exactly when lies in the column
space of (Theorem 3.1.1). Its
applications section then hit a wall. Traffic flows
cannot be negative, and once the unknowns are required
to satisfy , the column space is the wrong set to look
in. This section finds the right set, which is a
cone, and answers the new question with
the separation theorems of §03: either has a
non-negative solution, or a single vector certifies that it has
none. That is Farkas’s lemma, and the next two sections
run on it.
One step is harder than it looks. Separation needs a
closed set, and nothing proved so far
says that the relevant cone is closed. Most of the work
goes into that step, and the last part of the section
shows, with an explicit cone, that it can really
fail.
Throughout, the field is . Vectors in
are columns,
is the standard inner product, and
is the
Euclidean norm it induces, the norm that Theorem 18.3.1 uses.
Convergence means , and “closed” is meant in the
sequential sense of Definition 18.1.6: a set
is closed when
every limit of a convergent sequence of points of again lies in . Convergence in this
norm is entrywise convergence, by the elementary
bound
(18.5.1)
The left inequality holds because , and the right one is the triangle
inequality for . Applied to , with the
algebra of limits of Chapter 16’s introduction on the
right, it shows that
exactly when every entry of tends to .
Convex
cones
For a vector with real entries we write when
every entry of is , and when every
entry is .
The set is the non-negative orthant.
The relation is an entrywise statement about a vector,
and it has nothing to do with the Loewner order of Chapter
13, which is a statement about a matrix.
Here is the question. Let have columns . By Theorem 0.9.3, , so Without the sign condition this set would be
the span of the columns, a subspace. With it, the set is
closed under addition and under multiplication by
non-negative scalars, but not under
multiplication by . Such sets turn up
whenever quantities cannot be negative, so they get a
name.
A cone is a set you may stretch and add in, but
never reflect.
Definition
18.5.1 (Convex Cone)
Let be a
vector space over . A subset is a
convex cone if is
non-empty and
In words: a convex cone contains every
non-negative combination of two of its
members, and hence, by induction on the number of terms,
every non-negative combination of finitely many of its
members. Three special cases unpack the single
condition. Taking shows , so every convex cone contains the origin.
Taking shows
that is closed
under multiplication by non-negative scalars. Taking
shows
that it is closed under addition, and conversely a
non-empty set with these two closure properties is a
convex cone.
A convex cone is a convex set in the sense of Definition 18.1.1: take
and with . The
converse fails, and the next examples show how.
Examples. Each is checked against
the one condition of the definition.
- The orthant. If and , then every
entry of
is a sum of products of non-negative numbers, so . Hence
is a
convex cone.
- A half-space through the origin.
Fix
and let . If and , then . So
is a convex cone.
When it
is one of the two closed half-spaces bounded by the
hyperplane .
- The ice-cream cone. In , write vectors
as with
and
, and let
. If and , the triangle
inequality and homogeneity of the norm (Definition 16.1.1) give
. So
is a convex cone.
In it is the
round solid cone that gives the family its name.
- Positive semidefinite matrices. In
the real vector space of real symmetric matrices, the
set of
is a convex cone. This is part (a) of Exercise (C2: The cone of positive matrices).
Chapter 13 used the phrase there, and this is the
definition it was using.
- Degenerate cases. and are convex cones. More
generally, every subspace is a convex
cone, since it is closed under all linear
combinations and in particular the non-negative ones. A
subspace is the extreme case of a cone that happens to
be closed under reflection as well.
Non-examples by minimal change. In
, take the
union of two opposite quadrants, . It is closed under non-negative scaling,
since . The clause that fails is addition:
and lie in , but their sum does not. Or keep
convexity and lose the scaling: the closed unit disc is
convex, but
is not in it. Or translate the orthant to : it is
convex and closed under addition, but it does not
contain .
Why this definition. The scalars
must be non-negative. With all real scalars allowed, the
definition becomes the definition of a subspace, and the
sign information that started this section would be
lost. The requirement is a convention that some authors drop: they
call a cone as well. Including the origin costs
nothing here and keeps the statements below free of
exceptions.
Warning. A convex cone need
not be closed. In let It is a convex cone. Let and . The first
entry of
is . If it is positive, the vector lies in . If it is zero, then
and ; since the only
member of with
first entry is
, this forces
and , and the sum is
. But for every
, while the
limit is not
in . Separating a
point from a cone needs the cone to be closed, so
closedness must be proved. This particular cone comes
back at the end of the section as the image of a closed
cone.
The cones in the question at the start of this
section are the simplest kind.
Definition
18.5.2 (Finitely Generated Cone)
Let be vectors in a real vector space . The cone
generated by them is A cone of this form is finitely
generated. For the empty list we set , the value of the empty sum. When and is the matrix with
columns , this is , and we also
write it .
It is a convex cone: a non-negative combination of
two non-negative combinations of the is again one, with
coefficients . It is also the
smallest convex cone containing , since
any convex cone containing the contains all their
non-negative combinations, by the remark after Definition 18.5.1. The
orthant is . A subspace with basis is
, since is or
according to the sign of . The ice-cream cone is
not finitely generated, a fact we shall
neither need nor prove.
Quick check. Is in the same as ? Is a line or a half-line?
Solution. Both cones are the
quadrant . The second list’s cone is the quadrant
because . The first contains the second, and
every generator of the first lies in the quadrant, which
is a convex cone, so the first is contained in the
quadrant too. A redundant generator changes nothing. The
cone of and
is the
whole -axis ,
a line: for
use , and
for use
.
The dual
cone
A certificate that has no non-negative solution will be a
vector that
makes a non-negative inner product with every column of
but a negative
one with . Every
non-negative combination of the columns then also has a
non-negative inner product with , so cannot be such a
combination. The set of vectors that pass the first
test deserves a name.
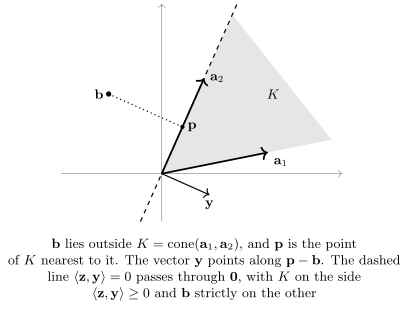
The dual cone of is the set of
directions that make an angle of at most with everything
in .
Definition
18.5.3 (Dual Cone)
Let be a
finite-dimensional real inner product space and let
be
any subset. The dual
cone of
is We write for .
In words: when the linear functional is
non-negative on the whole of , that is, when lies in the closed
half-space . The inner product is
what places
inside rather
than in the dual space of Chapter 5 (Theorem 5.1.1 is the case
).
Warning. is not the dual
space. The star here produces a subset of itself, not a space of
functionals, and it is defined for any subset, not only
for a subspace. For a subspace the dual cone is the
orthogonal complement: if for
every ,
then applying this to gives as
well, so , and the converse is immediate. So for a
subspace we always write , never .
The basic properties take one line each, and they
explain why every dual cone is a good set to separate
from.
Proposition
18.5.1 (Basic Properties of the Dual
Cone)
Let be a
finite-dimensional real inner product space and let
.
- (a) is a closed convex
cone.
- (b) If , then .
- (c) .
- (d) . In , with the matrix of columns
, this is .
Idea. is the intersection
of the sets , one for each . Parts (a), (b)
and (d) read off this description (more members of mean more conditions,
and for a cone the generators suffice), and (c) is the
symmetry of the inner product.
Proof.
(a) , so is non-empty. If
and ,
then for
every ,
using linearity in the second slot, which holds because
the field is .
Finally is an
intersection of closed half-spaces (all of when ), closed by Proposition 18.1.6 (c)
and (b), since is a
linear functional; if , then , which is
closed.
(b) A vector that
is non-negative against every member of is in particular
non-negative against every member of .
(c) If , then for
every ,
by the definition of . Since the inner
product is symmetric over , this says for
every ,
which is .
(d) The
generators lie in the cone, so (b) gives . Conversely, if
for every , then whenever every . The matrix
form follows because the -th entry of is .
Part (a) holds for every set , including one that is
neither convex nor closed. Part (c) is only an
inclusion, and the question of when it is an equality is
really the question of this section.
Examples.
- The orthant is its own dual. By
(d), .
- A single generator. , a closed
half-space when . A thin cone has a fat dual.
- The degenerate cases. The dual cone
of is all of
, and the dual
cone of is , because a in it must satisfy
, that is . As
subspaces, by the warning, we write these as and
.
- A wedge in the plane. For , part (d) gives . This is the wedge between the
directions
and , each
of which is perpendicular to one edge of . Exercise (B3: A dual cone and its dual)
finishes this computation.
Finitely
generated cones are closed
Now the key step. We want to separate a point from ,
and §03 separates points only from
closed convex sets. So we must show
that
is closed.
Here is why that is not obvious. Suppose with every
. The
obvious move is to take a limit of the , but they need not
converge, or even be bounded. If the columns of are dependent, then
can stay put
while runs off
along the null space. The cure has two parts. First,
throw away the dependence, generator by generator, which
is the “count, then drop a point” move of Theorem 18.2.2 adapted
to cones. Second, once the columns are independent,
prove that is
recovered from by a fixed linear
map, so that the cannot escape.
Theorem
18.5.2 (Carathéodory’s Theorem for
Cones)
Let be a real
vector space and let . Every lies in for some set of indices such that the list is
linearly independent. In particular, if
, then
is a
non-negative combination of at most of the .
Idea. Take a representation of
that uses as few
generators as possible. If those generators were
dependent, a dependence relation could be added to the
representation, with a scalar multiple chosen so that
one coefficient reaches zero and none goes negative.
That removes a generator, which contradicts minimality.
It is the move of Theorem 18.2.2 with a
linear dependence in place of an affine one,
and that difference is why the bound is rather than .
Proof. By Definition 18.5.2, with every . Discarding the
terms with ,
we can write with for every
, for some
. The empty set is allowed, when . Among all such
representations choose one with as small
as possible. We claim that is
linearly independent.
Suppose not. Then there are reals , for , not all zero,
with . Replacing every by if necessary, we may
assume that for at least one . Put a minimum over a non-empty finite set, so it
exists. It is , and it is attained at some . Then Every new coefficient is . If , then . If , then , so . Also .
Discarding the zero coefficients leaves a representation
of with positive
coefficients on a subset of ,
which contradicts the minimality of . Hence
is
linearly independent, and .
If , a
linearly independent list in has length at most
by Theorem 1.6.3 (a),
so . This proves the theorem.
The second part is a statement about one cone with
independent generators.
Lemma
18.5.3 (Injective Images of the Orthant Are
Closed)
Let have linearly independent
columns. Then is a closed subset of
.
Idea. Independent columns make
injective, and an injective matrix has a left inverse
with . So if converges, then
converges too, because is a fixed matrix. The
limit is still , and it maps to the limit of the . The left inverse
is what keeps the from running away,
and injectivity is exactly what provides it.
Proof. If , the cone is , which is closed.
Let . Since
the columns of
are linearly independent, Corollary 11.4.4
((b)
(c), with ,
where ) shows that is
invertible. Put , so
that .
Let with . Write with . Then .
By Eq. 18.5.1, entrywise.
Each entry of is a fixed linear
combination of the entries of , so by the algebra
of limits entrywise. Put .
Each entry of is , and a non-strict
inequality survives a limit, so . By the same
reasoning with the fixed matrix , we have
entrywise. A convergent sequence of real numbers has
only one limit, so . Hence with , that is, . This proves that the
cone is closed.
The two pieces now fit together.
Theorem
18.5.4 (Finitely Generated Cones Are
Closed)
Let . Then is a closed convex cone.
Idea. By Theorem 18.5.2 the cone
is the union of the cones of its independent sublists.
There are finitely many of them, and each is closed by
Lemma 18.5.3. A finite
union of closed sets is closed, by Proposition 18.1.6
(b).
Proof. Write , a convex cone by the remark after
Definition 18.5.2. Let
be the set of
those for which is
linearly independent, and for put . The empty set is in , and is finite, with at
most
members.
First, . Each , because a non-negative combination
of some of the
is a non-negative combination of all of them with the
remaining coefficients zero. And is Theorem 18.5.2.
Next, each
is closed. If , then . Otherwise , where is the matrix whose
columns are the with . Those columns
are linearly independent, so Lemma 18.5.3
applies.
Hence is a
finite union of closed sets, closed by Proposition 18.1.6
(b).
The proof uses no analysis beyond the algebra of
limits of Chapter 16’s introduction, through Eq. 18.5.1 and the
subsequence argument of Proposition 18.1.6 (b).
In particular it never uses compactness, fact (A3) (the
only compactness in the background would be the
equivalence of norms, which fixing the Euclidean norm
avoids); a finitely generated cone other than is unbounded, so
compactness had nothing to offer anyway. What the proof
uses is finite generation, twice: for
finitely many pieces, and for writing each piece as the
image of an orthant under a matrix with a left inverse.
The last part of the section shows that without it the
conclusion can fail. In Farkas’s lemma below,
compactness enters only through the existence half of Theorem 18.3.1.
Farkas’s
lemma
We can now separate. Theorem 18.3.2 would
give some hyperplane between and the cone, but for
a cone we want one through the origin,
with a normal vector whose sign on the cone we control.
Both come most cleanly from the nearest point of Theorem 18.3.1.
Lemma
18.5.5 (Separating a Point from a Closed
Cone)
Let be a
finite-dimensional real inner product space, let be a
closed convex cone, and let with . Then there
is
with .
Idea. Let be the point of nearest to , and use , the vector
from back to the
cone. The inequality of Theorem 18.3.1 says that
every point of is
seen from at an
angle of at least from . Because is a cone, we may test
it against and
, which shows
that the separating hyperplane passes through the
origin.
Proof. is non-empty, closed
and convex, so by Theorem 18.3.1 (a) there
is a point
nearest to , and
by part (b) of the same theorem
(18.5.2)
Put , which is non-zero since and . The points
and lie in , since is a cone. Substituting
them into Eq. 18.5.2 gives
and , so . Now
Eq. 18.5.2 reads , that is , for
every . So
.
Finally, since . This proves the lemma.
With , the lemma becomes the
theorem this section is named after. It is stated for a
matrix, since that is how it will be used.
Theorem
18.5.6 (Farkas’s Lemma)
Let and . Exactly one of the
following has a solution:
- (F1) with , ;
- (F2) and , with
.
Idea. The two systems cannot both
be solvable, which is one line of algebra: pair with . That at least one is
solvable is geometry. If (F1) fails, then lies outside the cone
of the columns, the cone is closed by Theorem 18.5.4, and Lemma 18.5.5 produces
.
Proof. Not both. Suppose
with
, and
.
Then since it is a sum of products of the
non-negative entries of and . So is
impossible.
At least one. Suppose (F1) has no solution.
Let . By Definition 18.5.2, (F1)
says exactly that , so . By Theorem 18.5.4, is a closed convex
cone, so Lemma 18.5.5 gives with . By Proposition 18.5.1 (d),
means
. So
solves (F2).
This proves the theorem.
The geometric reading. Either lies in the cone
spanned by the columns of , or there is a
hyperplane through the origin, , with every column on one side ()
and strictly on
the other (). The vector is a
certificate of infeasibility: anyone
can check (F2) by multiplying out, and the “not both”
computation then proves that (F1) has no solution.
Example
(Deciding a system both ways)
Let Decide, for and for , which
alternative of Theorem 18.5.6 holds,
and exhibit the solution.
Solution. The columns are , and , all in the
closed first quadrant. So , and in fact the two are equal,
since and
are among the
generators.
For
we expect (F1). The system , has, for
example, the solution , and also .
Non-negative solutions need not be unique.
For we expect (F2), since has a negative
first entry. Try : then and . So is a certificate, and by the “not both”
half of Theorem 18.5.6 the
system , has no solution. The certificate encodes a
one-line argument: the first equation reads , and its
left side is
whenever .
Linear programming, in the next section, meets
systems of inequalities, with . Farkas’s lemma
handles them after one standard move: add a
slack variable to turn each inequality
into an equation.
Corollary
18.5.7 (Farkas’s Lemma for Inequalities)
Let and . Exactly one of the following has a
solution:
- (i) with , ;
- (ii) , and , with
.
Idea. A slack vector
turns the inequalities into equations with matrix , and in Theorem 18.5.6 the
identity block becomes the extra condition .
Proof. Here means . So (i)
has a solution if and only if there are and in with : given
, take , and given
and , drop . In block form this
reads Apply Theorem 18.5.6 to the
matrix and to . Exactly one of the
system above and the following is solvable: and . The
transpose has the blocks and stacked, so the
first condition says and . That is (ii).
The dual
of the dual
Farkas’s lemma has a coordinate-free form, which says
that nothing is lost by passing to the dual cone twice,
provided the cone is closed.
Theorem
18.5.8 (The Bidual of a Closed Cone)
Let be a
finite-dimensional real inner product space and let
be a
closed convex cone. Then .
Proof. is Proposition 18.5.1 (c).
Conversely, let . By Lemma 18.5.5 there is
with
. That single shows . Hence
,
and the two are equal.
For , which is closed by Theorem 18.5.4, the
theorem is Farkas’s lemma. By Proposition 18.5.1 (d),
, so “” says that every with has , that is,
(F2) has no solution. And “” is (F1). This
is the “dualize” move in its purest form: a question
about a cone (is
in it?) is traded for one about its dual (does every
member of the dual approve of ?), and the trade is
exact when the cone is closed.
When the
cone is not finitely generated
The system “, ” asks whether lies in the image of
the orthant under . Replace the orthant by a closed convex
cone and by a matrix , and ask whether . The “not
both” half of the proof of Theorem 18.5.6 survives
unchanged. The “at least one” half needs to be closed, and
the next example shows that this can fail.
Example
(A closed cone with a non-closed shadow)
In , with
coordinates , let the set of triples for which the symmetric
matrix is
positive semidefinite (Definition 13.1.1).
Let , so that is
the projection onto the first two coordinates, and write
. Show that is a closed convex
cone, but that the cone of the earlier warning, which is not
closed. Then show that for
neither of the two alternatives
holds:
- (i) for some ;
- (ii)
for every ,
and , for some .
Solution. is a closed convex
cone. Write for . It is
linear in : . So if and
, then
for all , and
is a convex cone that contains . If with , then for
fixed the
number is a fixed linear combination of the entries
of . So it
converges to , and because a non-strict inequality
survives a limit. Hence is closed.
Membership. By Theorem 13.1.4 (a)
(e), exactly when the principal minors , and are all .
The image. . If and is arbitrary, put . Then , and , so and .
Conversely, if , then , and if then forces . So is exactly the
displayed set. It is not closed:
converges to .
Neither alternative holds for .
Alternative (i) fails because . For
(ii), suppose has
for every .
Since for every real , we get for all
. A non-constant
affine function of takes negative values,
so . But
then , which is not . So (ii) fails
too.
It is worth seeing exactly where the proof of Theorem 18.5.6 breaks.
The vectors lie in , their images converge to
, and the themselves run off
to infinity in the third coordinate. This is the escape
that the left inverse in Lemma 18.5.3 prevented.
There is no nearest point of to : the distance is , but is not in the set, so
Lemma 18.5.5 has nothing
to start from. What fails is
closedness, which is why the finitely
generated case needed its own theorem.
The dual cone cannot see the difference either: is the closed
half-plane , strictly larger than , as Exercise (C3: The bidual sees only the closure)
shows.
Exercises
A. Check your
understanding
Exercise
(A1)
- (a) Define a convex
cone and the dual cone of a subset of .
- (b) State Farkas’s
lemma, and say in one sentence what the vector in the second
alternative certifies.
- (c) Determine
whether the following is correct, and justify your
answer: every convex cone in is closed.
- (d) Determine
whether the following is correct, and justify your
answer: the union of two convex cones in is a convex
cone.
- (e) In Theorem 18.5.2 the bound
is generators,
while Theorem 18.2.2 allows
points. Which
feature of the proof accounts for the difference?
Solution.
(a) A convex cone
is a non-empty with for all and all real
. The
dual cone of is
.
(b) For and , exactly one of the following is
solvable:
with , or
with
.
Such a certifies
that the first system has no solution, since any
solution would
give .
(c) Incorrect.
The cone of the warning in this section
is a convex cone, but leaves it.
(d) Incorrect.
The two quadrants and are convex cones, and their union contains
and but not their sum
.
(e) For cones the
dependence to be removed is a linear
dependence , and a linearly independent list in an -dimensional space has
at most members.
For convex hulls it is an affine
dependence (coefficients also summing to ), and an affinely
independent list can have members.
B. Practice
Exercise
(B1: Recognizing cones)
Determine which of the following subsets of or are convex cones.
Justify your answers.
- (a) .
- (b) .
- (c) .
- (d) .
- (e) .
Solution.
(a) A convex
cone. It is non-empty, containing . If ,
and , then by the triangle inequality for real
numbers (Theorem 0.6.4) It is , a quarter-plane turned by .
(b) A convex
cone. It is a subspace, being the null space of , and every subspace is a convex
cone.
(c) Not a convex
cone: it does not contain , which taking in the
definition would force into it. It is convex and closed
under addition; what fails is scaling by , for
instance is not in it.
(d) Not a convex
cone. It is convex, but it is not closed under
non-negative scaling: is in it, and is not,
since .
(e) A convex
cone. Each of the three conditions is a homogeneous
linear inequality ,
with ,
and , so the set is
an intersection of three half-spaces through the origin.
Each is a convex cone by the examples of this section,
and an intersection of convex cones is a convex cone: it
contains , and
each member cone contains every non-negative combination
of points of the intersection.
Exercise
(B2: A certificate either way)
Let . For each of and , decide
which alternative of Theorem 18.5.6 holds,
and exhibit a solution of that alternative.
Solution. The columns are , and .
For ,
try : the equations and give . So
solves ,
and (F1) holds.
For , look for perpendicular to the
“outermost” generator and non-negative on
the others. The vector gives and . So (F2) holds, and by Theorem 18.5.6 the
system , has no solution. As a direct check, adding
twice the first equation to the second gives , whose
left side is
for .
Exercise
(B3: A dual cone and its dual)
Let .
- (a) Show that .
- (b) Compute and check that it
equals , as Theorem 18.5.8
predicts.
Solution.
(a) By Proposition 18.5.1 (d),
. Given such a , write : indeed the right side is , and both coefficients are . So .
Conversely, both generators satisfy the two
inequalities, and the set defined by the inequalities is
a convex cone, so it contains the cone they
generate.
(b) Applying Proposition 18.5.1 (d)
to the generators found in (a), . The same decomposition argument,
now with , shows this set is .
C. Going deeper
Exercise
(C1: Gordan’s alternative)
Let .
- (a) Prove that
exactly one of the following has a solution: with and ; or with
.
- (b) Deduce that if
the columns of
are , and , then some
non-trivial non-negative combination of them is , and find one.
Hint for (a): scale so that its entries
sum to , and apply
Theorem 18.5.6 to with an extra row of
ones.
Solution.
- (a) Not
both. If with , , and , then . Every term
is , and the
term for an index with is . That is a contradiction.
At least one. Suppose the first system has
no solution. If , and , then would solve it. So the system has no solution. By Theorem 18.5.6 there is
with and , that is, . Then , so solves the second
system.
- (b) Here . The second system is
impossible: , and its entries sum to , so they cannot all be
positive. By (a) the first system is solvable. Indeed
gives .
Exercise
(C2: The ice-cream cone is its own dual)
Let , with
the inner product on .
- (a) Prove that .
- (b) Prove that .
- (c) Deduce that
is closed.
Hint for (b): test against
the member of .
Solution.
(a) Let .
By Theorem 11.1.5,
, where the last
step multiplies the inequalities
and . Hence . Fix
: we
have shown that its inner product with every is , so . Hence
.
(b) Let . The
point lies in , so If , dividing by gives
.
If , test
against instead: . Either way .
(c) By (a) and
(b), , and
every dual cone is closed by Proposition 18.5.1
(a).
Exercise
(C3: The bidual sees only the closure)
Let , the
image cone of Example (A closed cone with a non-closed shadow).
- (a) Prove that .
- (b) Prove that .
- (c) Explain why this
does not contradict Theorem 18.5.8, and show
that is the
set of all limits of convergent sequences of points of
.
Solution.
(a) If ,
then testing against gives for every real . This forces , as in the
example, and then gives . Conversely, if and , then for every , since on .
(b) By (a), , so by Proposition 18.5.1 (d),
(c) Theorem 18.5.8 assumes
the cone is closed, and is not. Every point of
is such a
limit: if
or , use
the constant sequence; if , use , which tends to . Conversely, a
limit of points of lies in , because is closed by Proposition 18.5.1 (a).
So is
exactly the set of limits of sequences in .